Mortgage calculator
Enter the amount, the rate and the term to see the monthly payment, what the loan costs in total, and how the balance falls year by year.
Then add an extra amount per month. On a 30-year mortgage, a surprisingly small one removes years from the term.
- Amount borrowed$350,000
- Total interest$446,406
- Total repaid$796,406
A home monthly payment comes out of the Household share of your income — 35% on the 25-10-15-15-35 budget, which also has to cover everything else that share pays for.
Balance over time
What you still owe at the end of each year.
Year of the loan →
Year-by-year schedule30 years
| Year | Monthly payments paid | Towards the loan | Interest | Balance left |
|---|---|---|---|---|
| 1 | 12 | $3,912 | $22,635 | $346,088 |
| 2 | 12 | $4,174 | $22,373 | $341,914 |
| 3 | 12 | $4,454 | $22,093 | $337,460 |
| 4 | 12 | $4,752 | $21,795 | $332,709 |
| 5 | 12 | $5,070 | $21,477 | $327,638 |
| 6 | 12 | $5,410 | $21,137 | $322,229 |
| 7 | 12 | $5,772 | $20,775 | $316,457 |
| 8 | 12 | $6,158 | $20,388 | $310,298 |
| 9 | 12 | $6,571 | $19,976 | $303,727 |
| 10 | 12 | $7,011 | $19,536 | $296,716 |
| 11 | 12 | $7,481 | $19,066 | $289,236 |
| 12 | 12 | $7,982 | $18,565 | $281,254 |
| 13 | 12 | $8,516 | $18,031 | $272,738 |
| 14 | 12 | $9,086 | $17,460 | $263,652 |
| 15 | 12 | $9,695 | $16,852 | $253,957 |
| 16 | 12 | $10,344 | $16,203 | $243,613 |
| 17 | 12 | $11,037 | $15,510 | $232,576 |
| 18 | 12 | $11,776 | $14,771 | $220,800 |
| 19 | 12 | $12,565 | $13,982 | $208,235 |
| 20 | 12 | $13,406 | $13,141 | $194,828 |
| 21 | 12 | $14,304 | $12,243 | $180,524 |
| 22 | 12 | $15,262 | $11,285 | $165,262 |
| 23 | 12 | $16,284 | $10,263 | $148,978 |
| 24 | 12 | $17,375 | $9,172 | $131,603 |
| 25 | 12 | $18,538 | $8,008 | $113,065 |
| 26 | 12 | $19,780 | $6,767 | $93,285 |
| 27 | 12 | $21,105 | $5,442 | $72,180 |
| 28 | 12 | $22,518 | $4,029 | $49,662 |
| 29 | 12 | $24,026 | $2,521 | $25,635 |
| 30 | 12 | $25,635 | $912 | $0 |
Free, no sign-up. The calculation runs on your device — nothing you type is sent anywhere.
What a 30-year mortgage costs
$350,000 at 6.5% over 30 years is a payment of $2,212.24 a month in principal and interest. Across the full term you repay about $796,406 — $446,406 of it interest. You pay for the house roughly twice, which is the part the monthly figure is very good at hiding.
Note that this is principal and interest only. Property taxes, homeowners insurance, HOA fees and any mortgage insurance are additional, and together they often add a substantial amount to what actually leaves your account each month. Lenders quote them together as PITI; this calculator shows the loan itself.
What an extra $200 a month does
On that same $350,000 at 6.5%, adding $200 a month — about 9% more than the payment:
- Pays the mortgage off in 23 years and 10 months instead of 30 — 74 months early.
- Cuts total interest from $446,406 to about $338,309.
- Saves roughly $108,097.
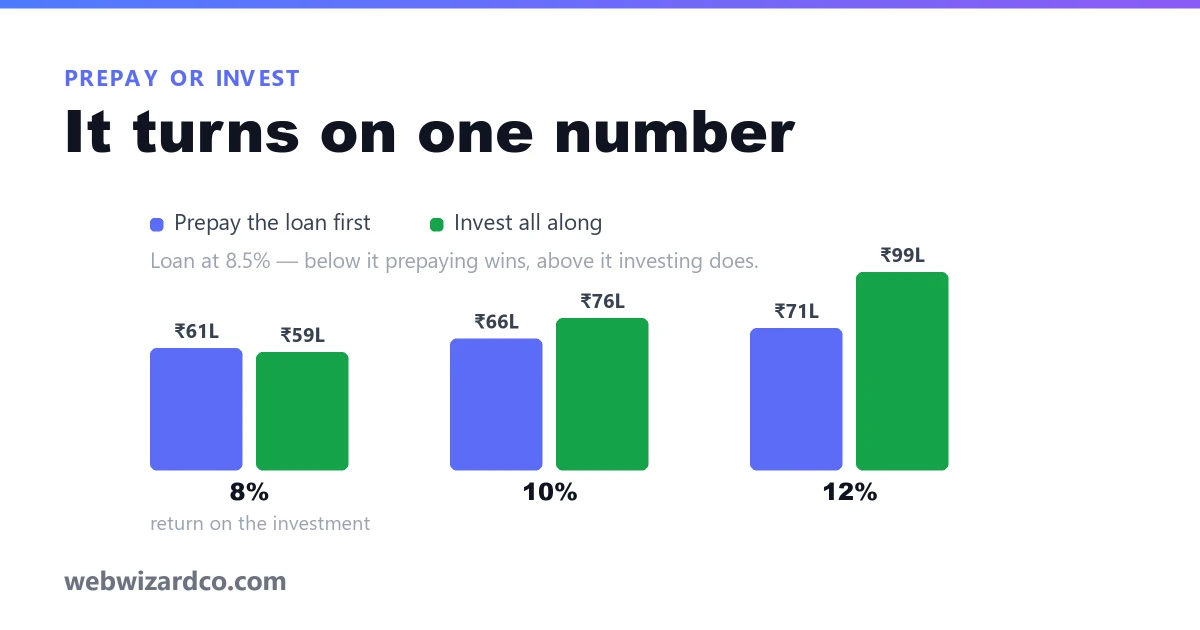
The reason the saving is so much larger than the money paid in is amortisation. Early payments are almost entirely interest, so anything extra goes straight against the balance and stops that balance charging interest for every remaining month of the loan. The same $200 added in year 25 saves almost nothing — timing is most of the effect.
Check whether your loan has a prepayment penalty before planning around this; most modern US fixed-rate mortgages do not, but it is worth confirming.
Shorter term, or extra payments?
A 15-year mortgage carries a lower rate and much less total interest, but the payment is considerably higher and you are committed to it. Taking the 30-year and paying extra voluntarily reaches a similar place with one advantage: in a bad month you can stop, and the required payment is still the lower one. The cost of that flexibility is the slightly higher rate on the longer term.
How much house is sensible
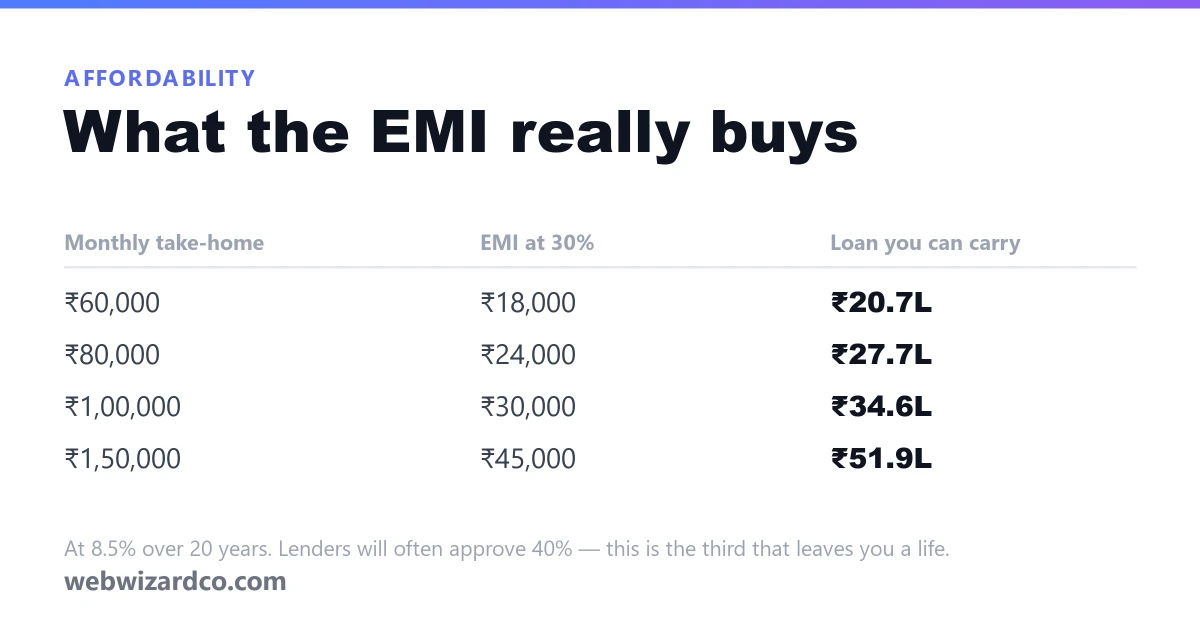
A common guideline is that housing costs should stay under about 28% of gross income, and total debt under about 36%. Those are lender thresholds, and like all lender thresholds they describe the edge of what is allowed rather than what is comfortable.
The more useful version is to work from take-home pay and what is left after the payment. Enter your monthly take-home above to see the payment as a share of it, and use a monthly budget to check what the rest of the household still needs once the mortgage is paid.
Other calculators
Worth reading first
How to use this calculator
Three inputs, and one optional field that most calculators leave out.
Enter the amount, rate and tenure
Type them in or drag the sliders. The monthly payment and the total interest update as you go.
Add an extra monthly amount
Optional, and the most useful box on the page: it shows how many years a small regular overpayment removes, and what that saves in interest.
Check it against your income
Enter your monthly take-home pay to see the monthly payment as a share of it, then look at the year-by-year schedule to see how slowly the balance moves at the start.