Car loan EMI calculator
Car loans are sold on the monthly figure, usually while you are sitting in a showroom and have already decided. This works out what the loan costs in total, which is the number the EMI is designed to make you stop thinking about.
- Amount borrowed₹8,00,000
- Total interest₹2,98,316
- Total repaid₹10,98,316
A vehicle EMI comes out of the Travel & car share of your income — 15% on the 25-10-15-15-35 budget, which also has to cover everything else that share pays for.
Balance over time
What you still owe at the end of each year.
Year of the loan →
Year-by-year schedule7 years
| Year | EMIs paid | Towards the loan | Interest | Balance left |
|---|---|---|---|---|
| 1 | 12 | ₹84,519 | ₹72,383 | ₹7,15,481 |
| 2 | 12 | ₹92,908 | ₹63,994 | ₹6,22,573 |
| 3 | 12 | ₹1,02,129 | ₹54,774 | ₹5,20,444 |
| 4 | 12 | ₹1,12,265 | ₹44,637 | ₹4,08,179 |
| 5 | 12 | ₹1,23,407 | ₹33,495 | ₹2,84,773 |
| 6 | 12 | ₹1,35,655 | ₹21,248 | ₹1,49,118 |
| 7 | 12 | ₹1,49,118 | ₹7,784 | ₹0 |
Free, no sign-up. The calculation runs on your device — nothing you type is sent anywhere.
The tenure trap
₹8,00,000 at 9.5% over 7 years is an EMI of ₹13,075, and ₹2,98,316 of interest. The same loan over 5 years is an EMI of ₹16,801 and ₹2,08,089 of interest.
The longer tenure saves ₹3,726 a month and costs ₹90,227 more. Dealers lead with the seven-year figure because it makes a more expensive car look affordable — the monthly number is what is being sold, not the car.
A car is not a house
The other half of the maths never appears on the loan document. A new car loses value from the day it is registered, typically a large share of it in the first three years, while the loan balance falls slowly at the start. On a long tenure with a small down payment, it is entirely normal to owe more than the car is worth for the first several years — which matters the moment you need to sell it, or it is written off.
Two things fix this, and both are unpopular in showrooms: a larger down payment, and the shortest tenure whose EMI you can genuinely afford.
Watch for a flat rate
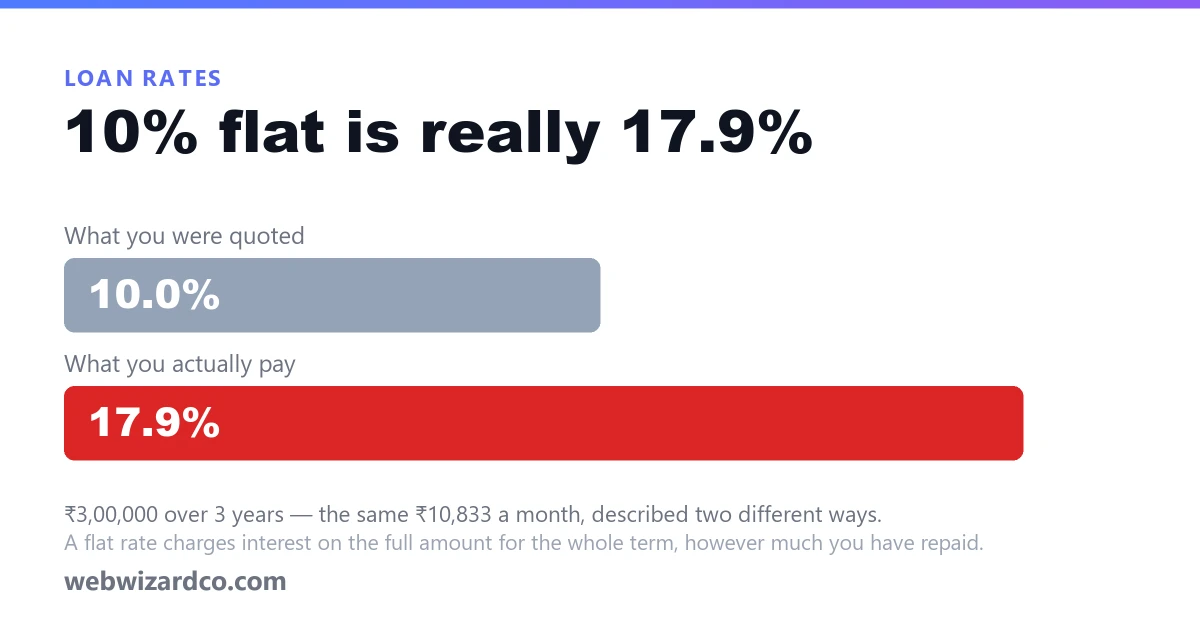
Two-wheeler and used-car finance is often quoted as a flat rate, where interest is charged on the full original amount for the whole term regardless of what you have repaid. A "10% flat" loan works out at roughly 18% reducing balance — the basis every bank EMI here is calculated on. If the rate you have been quoted looks unusually good, ask which of the two it is.
Where it fits in a budget
On the 25-10-15-15-35 split, a car EMI comes out of the 15% for travel and vehicles — and it has to share that share with fuel, servicing, insurance, parking and tolls. On a ₹60,000 salary that whole bucket is ₹9,000 a month, which a ₹13,075 EMI exceeds on its own before a single litre of fuel.
That does not make the car impossible; it makes it a decision about what else gives way. Enter your take-home pay above to see the EMI as a share of it, and track what the car actually costs you once it is on the road — the running costs are usually a bigger surprise than the EMI.
Other calculators
Worth reading first
How to use this calculator
Three inputs, and one optional field that most calculators leave out.
Enter the amount, rate and tenure
Type them in or drag the sliders. The EMI and the total interest update as you go.
Add an extra monthly amount
Optional, and the most useful box on the page: it shows how many years a small regular overpayment removes, and what that saves in interest.
Check it against your income
Enter your monthly take-home pay to see the EMI as a share of it, then look at the year-by-year schedule to see how slowly the balance moves at the start.